
GST Registration & Return Filings in India: Complete Compliance Guide for 2026
This article is for general informational purposes and does not constitute tax or legal advice. GST rules are subject to government notification and change — verify current requirements on the official GST portal or with a qualified tax professional.
Operating a business in India requires strict adherence to various regulatory frameworks, with Goods and Services Tax (GST) being one of the most critical components of your overall business compliance. As a vital cluster topic under the broader umbrella of mandatory business reporting, maintaining your GST health is non-negotiable. For a macro view of all mandatory corporate and tax filings, including RoC, TDS, and Labour Law compliances, explore our comprehensive pillar guide on Statutory Compliance Filings.
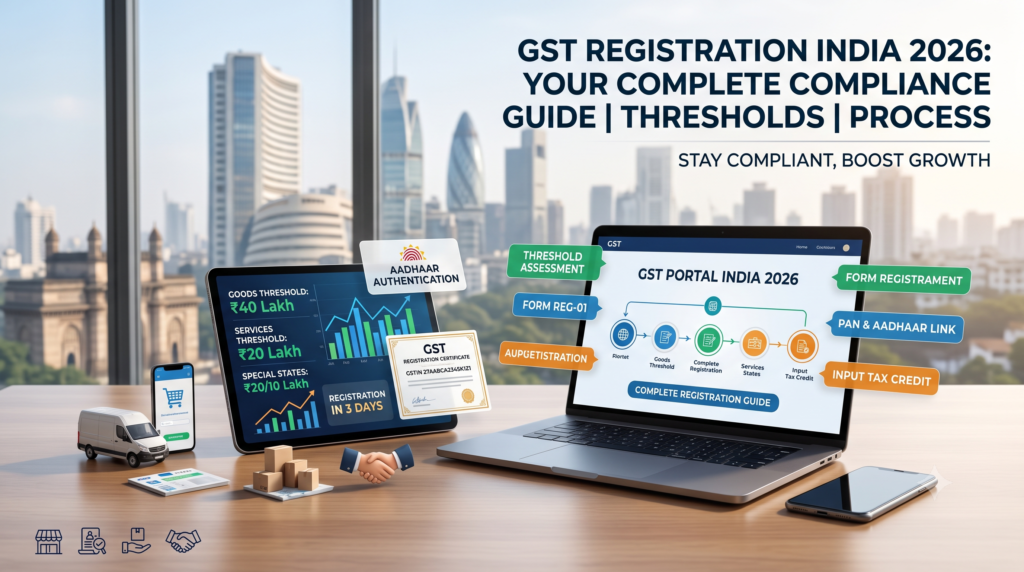
Quick Answer: GST registration becomes mandatory in India when a business's aggregate annual turnover exceeds ₹40 lakh for suppliers of goods (₹20 lakh in special category states) or ₹20 lakh for suppliers of services (₹10 lakh in special category states). Certain categories — including e-commerce sellers, interstate suppliers, casual taxable persons, and businesses under reverse charge — must register regardless of turnover. Once you cross the applicable threshold, you have 30 days to apply for registration on the GST portal using Form GST REG-01. Low-risk applicants using Aadhaar authentication can now receive registration within 3 working days under a simplified route, while standard applications are typically processed within 7 working days. Failure to register on time attracts a penalty of 10% of the tax due, or a minimum of ₹10,000, whichever is higher.
What Is GST Registration?
GST (Goods and Services Tax) registration is the process by which a business becomes formally recognized under India's indirect tax system and receives a GSTIN (GST Identification Number) — a unique 15-digit identifier tied to the business's PAN. Once registered, a business can legally collect GST from customers, claim Input Tax Credit (ITC) on purchases, and issue GST-compliant invoices. Operating above the threshold without registration is a compliance violation with severe financial and legal consequences. Furthermore, GST interacts deeply with other statutory compliance filings, as income reported under GST is routinely cross-referenced by the Income Tax Department.GST Registration Threshold Limits (2026)
| Category | Normal States | Special Category States |
|---|---|---|
| Suppliers of goods only | ₹40 lakh | ₹20 lakh |
| Suppliers of services (or mixed supplies) | ₹20 lakh | ₹10 lakh |
Who Must Register Regardless of Turnover
Certain categories are required to register under GST even with zero or minimal turnover, because of the nature of their business activity rather than their revenue:- ✓E-commerce Operators & Sellers on e-commerce platforms (Amazon, Flipkart, etc.).
- ✓Interstate Suppliers of taxable goods (services have a partial exemption below the standard threshold).
- ✓Casual Taxable Persons supplying goods/services occasionally in a state without a fixed place of business (e.g., at a trade fair or exhibition).
- ✓Non-Resident Taxable Persons supplying goods or services in India.
- ✓Reverse Charge Mechanism (RCM): Persons liable to pay tax under RCM provisions.
- ✓TDS/TCS Deductors: Entities required to deduct TDS or collect TCS under GST provisions.
- ✓Input Service Distributors (ISDs) and agents making taxable supplies on behalf of a principal.
- ✓OIDAR Service Providers: Online Information and Database Access or Retrieval service providers based outside India, serving unregistered customers in India.
GST Registration Process — Step by Step
- Check Applicability: Confirm whether your turnover has crossed the relevant threshold, or whether you fall into a mandatory-registration category regardless of turnover.
- Gather Documents: PAN card, Aadhaar card, proof of business constitution (partnership deed, certificate of incorporation, etc.), address proof of the place of business, bank account details/statement, and a photograph of the proprietor/partners/directors.
- File Form GST REG-01 on the official GST portal (gst.gov.in), providing business details, principal place of business, and authorized signatory information.
- Aadhaar Authentication: Low-risk applicants who complete Aadhaar authentication can be approved through a simplified route within 3 working days without officer intervention.
- Receive ARN: An Application Reference Number is generated and sent via email and SMS once the application is submitted.
- Verification: For applications flagged for scrutiny, a GST officer may request additional documents or conduct physical verification of the business premises, which can extend processing to around 7 working days or more.
- Certificate Issuance: Once approved, the GST Registration Certificate and GSTIN are issued electronically.
Types of GST Registrations
While regular registration applies to most domestic businesses, the GST framework includes specific registration categories depending on the nature of operations:- ✓Normal Taxpayer: The standard registration for businesses operating continuously within a state.
- ✓Composition Taxpayer: Aimed at small businesses with turnover up to ₹1.5 crore, allowing them to pay a flat tax rate without the burden of complex monthly returns.
- ✓Casual Taxable Person: For temporary businesses, such as a vendor setting up a stall in an exhibition in a state where they have no permanent place of business. This registration is valid for 90 days.
- ✓Non-Resident Taxable Person: For individuals or businesses located outside India but occasionally supplying goods or services within India.
Post-Registration: The Core of GST Returns Filing
Obtaining a GSTIN is merely the first step. The ongoing requirement involves periodic GST returns, which form the bedrock of your statutory compliance filings. Failing to file these returns not only blocks your buyers from claiming Input Tax Credit but also invites hefty late fees.Major GST Returns include:
- GSTR-1 (Details of Outward Supplies): Filed monthly or quarterly (under the QRMP scheme). It contains invoice-level details of all sales and outward supplies made by the business.
- GSTR-3B (Summary Return & Tax Payment): Filed monthly or quarterly. This is a self-declared summary of outward supplies, input tax credit claimed, and net tax payable. The actual tax payment is made during the filing of GSTR-3B.
- GSTR-9 (Annual Return): A comprehensive yearly return that consolidates all monthly/quarterly filings. It reconciles the data reported in GSTR-1 and GSTR-3B throughout the financial year.
- GSTR-9C (Reconciliation Statement): Required for businesses with an annual turnover exceeding ₹5 crore. It is a self-certified reconciliation statement matching the audited financial statements with the GSTR-9.
Input Tax Credit (ITC) Rules and GSTR-2B Matching
One of the most heavily scrutinized areas by tax authorities is Input Tax Credit. You can only claim ITC if your supplier has uploaded the invoice in their GSTR-1, and it subsequently reflects in your dynamically generated GSTR-2B statement.If an invoice is not visible in your GSTR-2B, you cannot claim the credit, even if you possess a physical copy of the invoice and have paid the supplier. Continuous reconciliation between purchase registers and GSTR-2B is now a mandatory monthly compliance routine for all regular taxpayers.
What's New in GST for 2026
- ✓Rate Rationalization (GST 2.0): Effective from September 2025 and carried forward through 2026, the GST slab structure has been simplified to primarily 0%, 5%, and 18%, with a 40% rate retained for specified luxury and "sin" goods — the earlier 12% and 28% slabs no longer apply to most goods and services.
- ✓3-Year Return Filing Time-Bar: From December 2025, GST returns older than three years from their original due date can no longer be filed at all — a hard cutoff enforced at the portal level. Businesses with pending old filings should clear them urgently.
- ✓Simplified Fast-Track Registration (CGST Rule 14A): Small suppliers with monthly output tax liability below ₹2.5 lakh can use a streamlined, Aadhaar-authenticated registration route with faster turnaround.
- ✓Mandatory Bank Account Verification: Registered businesses must keep bank account details updated and verified on the portal; failure to do so can result in automatic suspension of the GSTIN, which blocks return filing and e-way bill generation.
- ✓Stricter E-Invoicing Timelines: Businesses with Aggregate Annual Turnover (AATO) above ₹10 crore must report e-invoices to the Invoice Registration Portal (IRP) within 30 days of the invoice date, after which IRN generation is blocked for that document.
- ✓Annual Re-Assessment of Registration Status: Businesses are expected to recheck their turnover at the start of each financial year, since crossing the threshold makes registration mandatory even if it wasn't required in prior years.
E-Way Bills and E-Invoicing Integration
Statutory compliance under GST is highly digitized.E-Way Bills: Movement of goods worth more than ₹50,000 (interstate or intrastate) requires the generation of an E-Way Bill on the common portal. It ensures that goods being transported comply with the GST laws and prevents tax evasion.
E-Invoicing: As of recent updates, e-invoicing is mandatory for businesses with an aggregate annual turnover exceeding ₹5 crore. B2B invoices must be authenticated by the Invoice Registration Portal (IRP), which issues an Invoice Reference Number (IRN) and a QR code. Traditional manual invoices issued by applicable businesses are considered invalid and can lead to penalties.
Voluntary GST Registration
Businesses below the mandatory threshold can still choose to register voluntarily. Common reasons include:- ✓Input Tax Credit: Ability to claim Input Tax Credit on business purchases.
- ✓Improved Credibility: Builds trust with larger clients and B2B customers who prefer dealing with GST-registered vendors.
- ✓Seamless Growth: Easier expansion into interstate or e-commerce sales later without a registration delay.
- ✓Tender Eligibility: Access to government tenders and corporate contracts that require a valid GSTIN.
Consequences of Not Registering or Filing on Time
Compliance failures are heavily penalized under the GST Act. These repercussions make timely filings one of the most important aspects of your overall statutory framework:- Financial Penalty for Non-Registration: 10% of the tax due, or a minimum of ₹10,000, whichever is higher, under Section 122 of the CGST Act.
- Late Fees on Returns: ₹50 per day (₹20 for nil returns) for delayed filing of GSTR-3B and GSTR-1, subject to a maximum cap that scales with the business's turnover.
- Interest on Late Payment: 18% per annum interest is levied on the net tax liability paid after the due date.
- Suspension of E-Way Bills: If a taxpayer fails to file returns for two consecutive tax periods, their GSTIN is blocked from generating E-Way Bills, effectively halting the movement of goods.
- Loss of Input Tax Credit: Unregistered businesses cannot claim ITC on their purchases, increasing effective costs.
The Composition Scheme — An Alternative for Small Businesses
Small taxpayers with aggregate turnover up to ₹1.5 crore (₹75 lakh in special category states) can opt for the Composition Scheme instead of regular GST registration. Under this scheme, businesses pay a fixed, lower percentage of turnover as tax (typically 1–6%, depending on the business type) and file simplified quarterly returns (CMP-08), but cannot claim Input Tax Credit. This can suit small traders and service providers with limited B2B purchases, but is generally less advantageous for businesses that rely heavily on ITC to manage costs.Frequently Asked Questions
- Q: Is the GST registration limit ₹20 lakh or ₹40 lakh?
A: It depends on what you supply. Goods-only suppliers in normal states have a ₹40 lakh threshold; service providers (or mixed goods-and-services suppliers) have a ₹20 lakh threshold. Special category states have lower limits of ₹20 lakh and ₹10 lakh respectively. - Q: How long does it take to get a GST registration certificate?
A: Low-risk, Aadhaar-authenticated applications can be approved within 3 working days. Standard applications, or those flagged for additional verification, typically take around 7 working days. - Q: Do I need GST registration if I sell on Amazon or Flipkart?
A: Yes. E-commerce sellers are required to register for GST regardless of turnover, since platforms are required to collect Tax Collected at Source (TCS) on their sales. - Q: What happens if I don't register after crossing the threshold?
A: You become liable for a penalty of 10% of the tax due or ₹10,000, whichever is higher, along with potential loss of Input Tax Credit and exposure to scrutiny or notices from the GST department. - Q: Can I register for GST voluntarily even if I'm below the threshold?
A: Yes. Voluntary registration is available at any time and can be beneficial for claiming ITC and building credibility with B2B clients. - Q: How does GST compliance relate to other statutory filings?
A: Your reported GST turnover is frequently cross-matched with your Income Tax Returns (ITR) and TDS filings. Discrepancies between your GST portal data and other corporate filings often trigger automated notices from tax authorities.
The Big Picture
Given the number of moving parts — threshold calculations across multiple business verticals, mandatory-registration categories, document requirements, monthly reconciliations, and the choice between regular and composition registration — many businesses prefer professional guidance to avoid delays or errors in their application and ongoing returns.Managing GST is a continuous responsibility that demands rigorous attention to detail. It is best handled alongside your wider corporate governance and statutory compliance filings to ensure unified reporting and tax optimization.
✓ Takeaway: GST rules, thresholds, and rates are subject to notification and change by the GST Council and government. This article reflects publicly available guidance as of mid-2026. Partner with expert HVJ's GST registration services to handle end-to-end registration, threshold assessment, and ongoing compliance support for businesses of all sizes.
Latest Blog